Last Updated on September 27, 2026
How Your Employment History and Income Impact Mortgage Approval
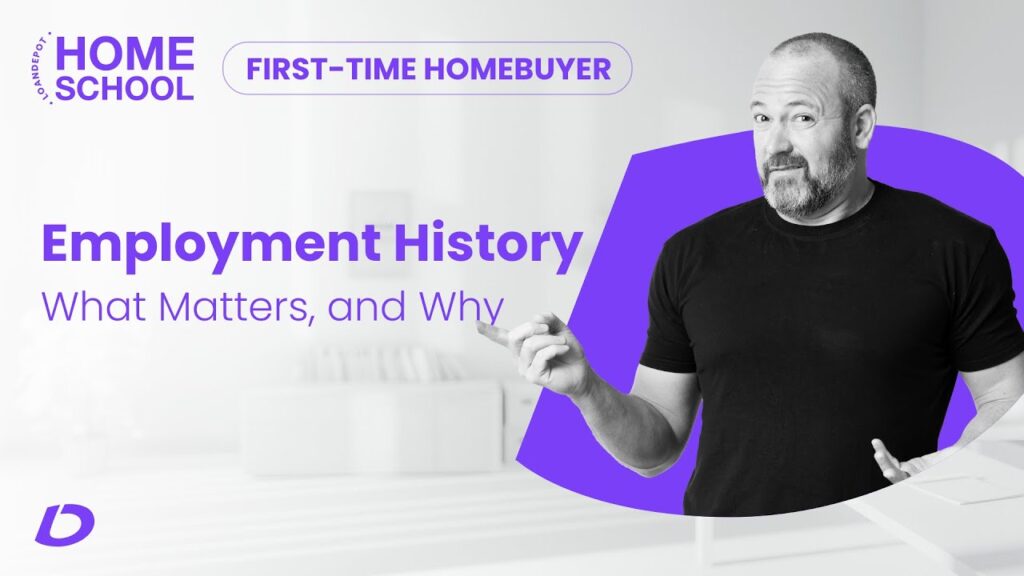
When you apply for a home loan, lenders aren’t just looking at your bank balance; they are looking for stability. One of the most common questions prospective buyers have is how their career path and paycheck details affect their chances of success. In this edition of “Home School,” loanDepot provides a clear breakdown of employment history requirements and what counts as qualifying income.
Understanding these guidelines early can help you navigate the mortgage approval process with confidence, even if your professional journey has had a few twists and turns.
Main Takeaways
- The Two-Year Standard: Lenders generally look for two years of continuous employment within the same industry to establish a pattern of stability.
- Acceptable Gaps: Life events like disability, re-entering the workforce after parenting, or temporary union work gaps are often viewed as valid exceptions.
- Diverse Income Sources: Beyond standard wages, income from self-employment, pensions, alimony, and government benefits can help you qualify.
- Documentation is Key: Having your W-2s, tax returns, and pay stubs organized is essential for a smooth underwriting process.
- The Overtime Rule: While overtime can count toward your income, you must be able to prove it is guaranteed and consistent.
Understanding the “Two-Year Rule”
As loanDepot points out, the baseline for most mortgage lenders is a 24-month history of steady work. This doesn’t necessarily mean you must be at the same company, but staying in the same line of work demonstrates to a lender that your income is reliable and likely to continue.
However, a “gap” on your resume isn’t an automatic disqualifier. Lenders are often willing to work with borrowers who have experienced:
- Disability: Periods where you were unable to work due to medical reasons.
- Stay-at-Home Parenting: Parents re-entering the workforce after dedicated time with family.
- Union Work Fluctuations: Short periods (typically 30-40 days) where union assignments may have paused.
Expanding the Definition of Qualifying Income
One piece of excellent advice from loanDepot is to remember that qualifying income comes in many forms. When calculating your debt-to-income ratio, lenders may consider:
- Self-Employment Income: For entrepreneurs and freelancers (requires detailed tax returns).
- Retirement & Benefits: Pensions and social security payments.
- Family Support: Court-ordered child support or alimony payments.
- Government Benefits: Stable assistance programs that provide regular cash flow.
A “side note” for those who rely on overtime or bonuses: while this money is great for your savings, lenders may only include it in your qualification if you can prove it is a guaranteed part of your compensation package.
Get Your Documents in Order
To move from “looking” to “closing,” you need to prove your financial story on paper. loanDepot recommends gathering these essential documents before you even apply:
- W-2s from the last two years.
- Federal Tax Returns (especially important for the self-employed).
- Recent Pay Stubs (usually the last 30 days).
- Bank Statements to show your assets and down payment funds.
Find Your Path to Approval with loanDepot
Every borrower’s story is unique. Whether you’ve recently changed careers, are self-employed, or are re-entering the workforce, the experts at loanDepot are here to help you understand your options and provide the home buying tips you need to succeed.
Ready to see where you stand?
- Get Free Monitoring: Take advantage of loanDepot’s free credit monitoring service to stay up to date with any changes in your profile.
- Talk to a Specialist: Contact a loanDepot professional today to discuss how your current score impacts your mortgage options and what steps you can take to qualify for the best possible rates.
Transcript: How Employment History Affects Your Mortgage Approval
In this installment of loanDepot’s “Home School” series, the lesson covers how your professional background and income types influence your ability to secure a home loan. The video aims to demystify the “two-year rule” and explains what lenders consider “qualifying income.”
The Two-Year Rule and Exceptions
Standard mortgage guidelines typically require two years of continuous employment in the same line of work to demonstrate stability. [00:13] However, lenders understand that life happens, and there are several acceptable “gaps” in employment, including:
- Disability leave. [00:32]
- Short periods (30–40 days) without union work. [00:32]
- Stay-at-home parents re-entering the workforce. [00:40]
What Counts as Qualifying Income?
Lenders look beyond just a standard base salary when determining how much you can afford. [00:53] Potential sources of qualifying income include:
- Regular wages and self-employment earnings. [01:00]
- Pensions and government benefits. [01:08]
- Child support and alimony. [01:08]
- Overtime: This can sometimes be included, but it is often difficult to use because you must prove that the extra pay is guaranteed moving forward. [01:16]
Preparing Your Documentation
To ensure a smooth approval process, the video recommends having your financial paperwork organized and ready to share with your lender. [01:22] Essential documents usually include:
The video concludes by encouraging potential buyers to discuss their unique personal situations with a professional, as exceptions are more common than many people realize. [01:41]